Home › Advice › Roofing › Storm Chaser Roofers: What to Check Before You Sign
Storm Chaser Roofers: What to Check Before You Sign
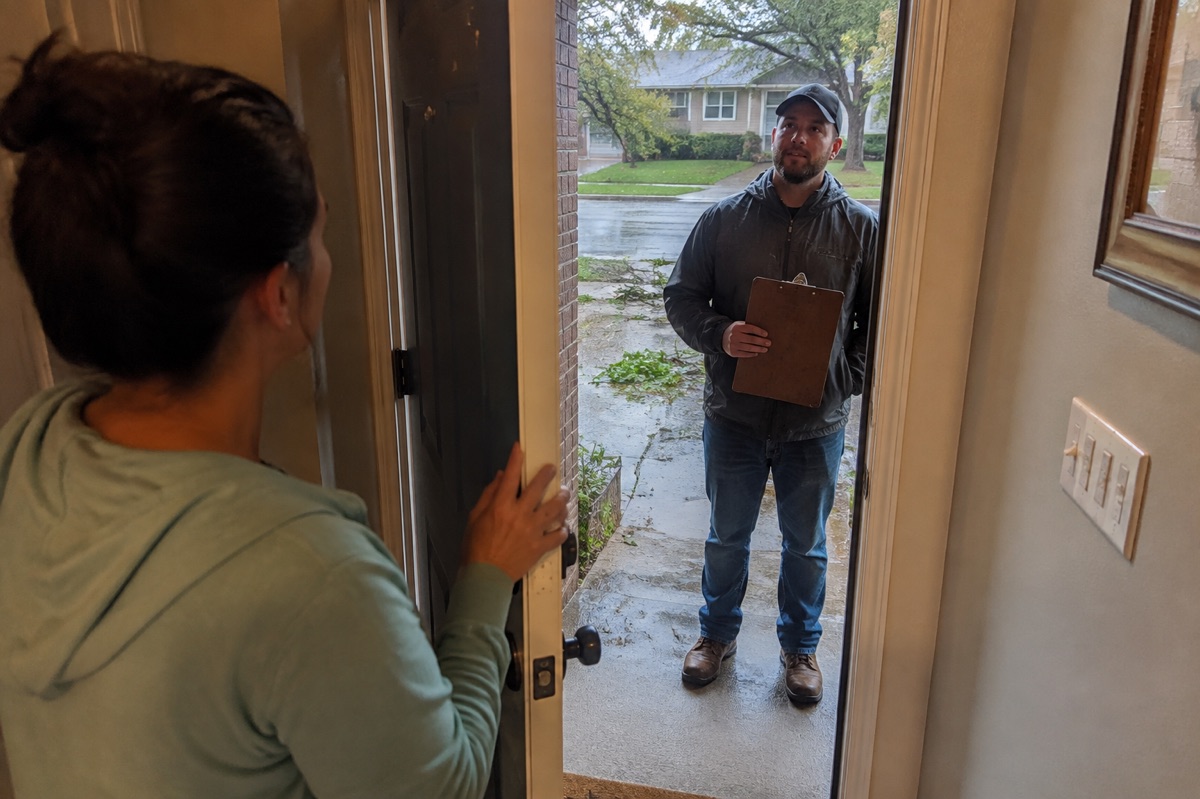
After a storm, check the offer before you sign. A roofer who travels or knocks on doors is not always a scammer. Pause if names are unclear or a form has blank fields. Be wary of a promise that your insurer will pay. Keep urgent safety work separate from a deal for a whole new roof.
Put safety and records first
Stay off a damaged roof. Keep away from loose wires, fallen trees, and a sagging ceiling. If the home is unsafe, leave. Call 911 for an urgent threat to life. Report downed power lines to the utility.
Contact your insurer through a number on your policy. Ask about the claim process, safe temporary work, and the records it needs. A seller at the door cannot decide what your policy covers.
Take photos from a safe place before work starts. Save receipts, texts, and emails. Our first roof leak steps can help you limit indoor harm. None of those steps asks you to get on the roof.
Check the firm behind the offer
Get the firm's legal name, contact address, and license number where required. Match them to the bid. Use an official record rather than a screenshot supplied by the seller.
Read our license check guide for state differences. A license does not prove every claim about skill or insurance. Confirm coverage with the agent or insurer and ask who will do the work.
Ask how you will get service after this storm season. A local office is useful contact information, not a promise that a firm will last. An out-of-town address is not proof of fraud either.
Keep emergency work narrow
A safe temporary cover and a full roof replacement are different jobs. Ask for the emergency scope and price in writing. Know whether the document also commits you to later work.
The FTC warns about storm offers that demand quick decisions or payment before facts can be checked. Do not sign blank fields or rely on “we will fill that in later.”
For larger work, seek more than one written bid if it is safe to wait. Compare the same scope. Use our roof quote guide to note missing work and unclear costs.
Read claim-rights language with care
An assignment of benefits, or AOB, transfers specified policy rights or benefits to another party. It is not just a form that lets a roofer inspect damage.
Florida DFS says post-loss benefit assignments are barred for residential or commercial property policies issued or renewed on or after January 1, 2023. Older policies and other states need their own review. Do not rely on old Florida AOB advice for a current policy.
Ask your insurer or a lawyer about any form that shifts rights to someone else. A roofer can give you photos and a repair scope. That does not mean the insurer must pay. Keep the claim decision separate from the sales pitch.
Check money and contract terms
Ask for dates, work details, product names, payment stages, and change terms. Check your state's deposit limits. Do not pay the full job price before work begins.
Keep a copy signed by both parties. Record who gets permits and who handles required inspections. If the seller says a permit is not needed, confirm with the local office.
Use our contract checklist to cover these points. Cash-only pressure, missing receipts, or a refusal to name the business should stop the sale until resolved.
If you have already signed
Save the contract, sales messages, photos, checks, and receipts. Write a dated account of what happened. Check for cancellation terms and notice deadlines right away.
Seek prompt help from a lawyer or your state consumer office. Show them what you signed. Tell them where and how the sale took place and what work was done. State law and those facts can change your rights. Do not assume every sale has the same cooling-off period.
Do not blindly stop payments or cancel a check based on a web guide. Get advice about your duties and options first. Report suspected fraud through official channels, but do not treat a complaint as a substitute for a timely contract notice.
Quick answers
- Does an out-of-town roofer mean a scam?
- No. Travel or door-to-door sales alone do not prove fraud. Verify the firm, legal scope, insurance, written bid, and service plan.
- Can a Florida roofer ask for an assignment of benefits?
- Florida bars post-loss benefit assignments for residential or commercial property policies issued or renewed on or after January 1, 2023. Ask the insurer or a lawyer about your exact policy and document.
- What should I do if I already signed?
- Save all records, check any notice deadline, and seek prompt help from a lawyer or consumer office. Do not assume you can cancel or stop payment without consequences.
Keep your home plan moving
Get the free Seasonal Home Maintenance Schedule
A seasonal checklist for your roof, gutters, HVAC and more, plus practical homeowner tips. Adjust the schedule for your climate and equipment.
We don't sell your email address. See our privacy policy.
Sources
- Avoid scams after weather emergencies — Federal Trade Commission
- Assignment of benefits — Florida Department of Financial Services
- Avoid home improvement scams — Federal Trade Commission